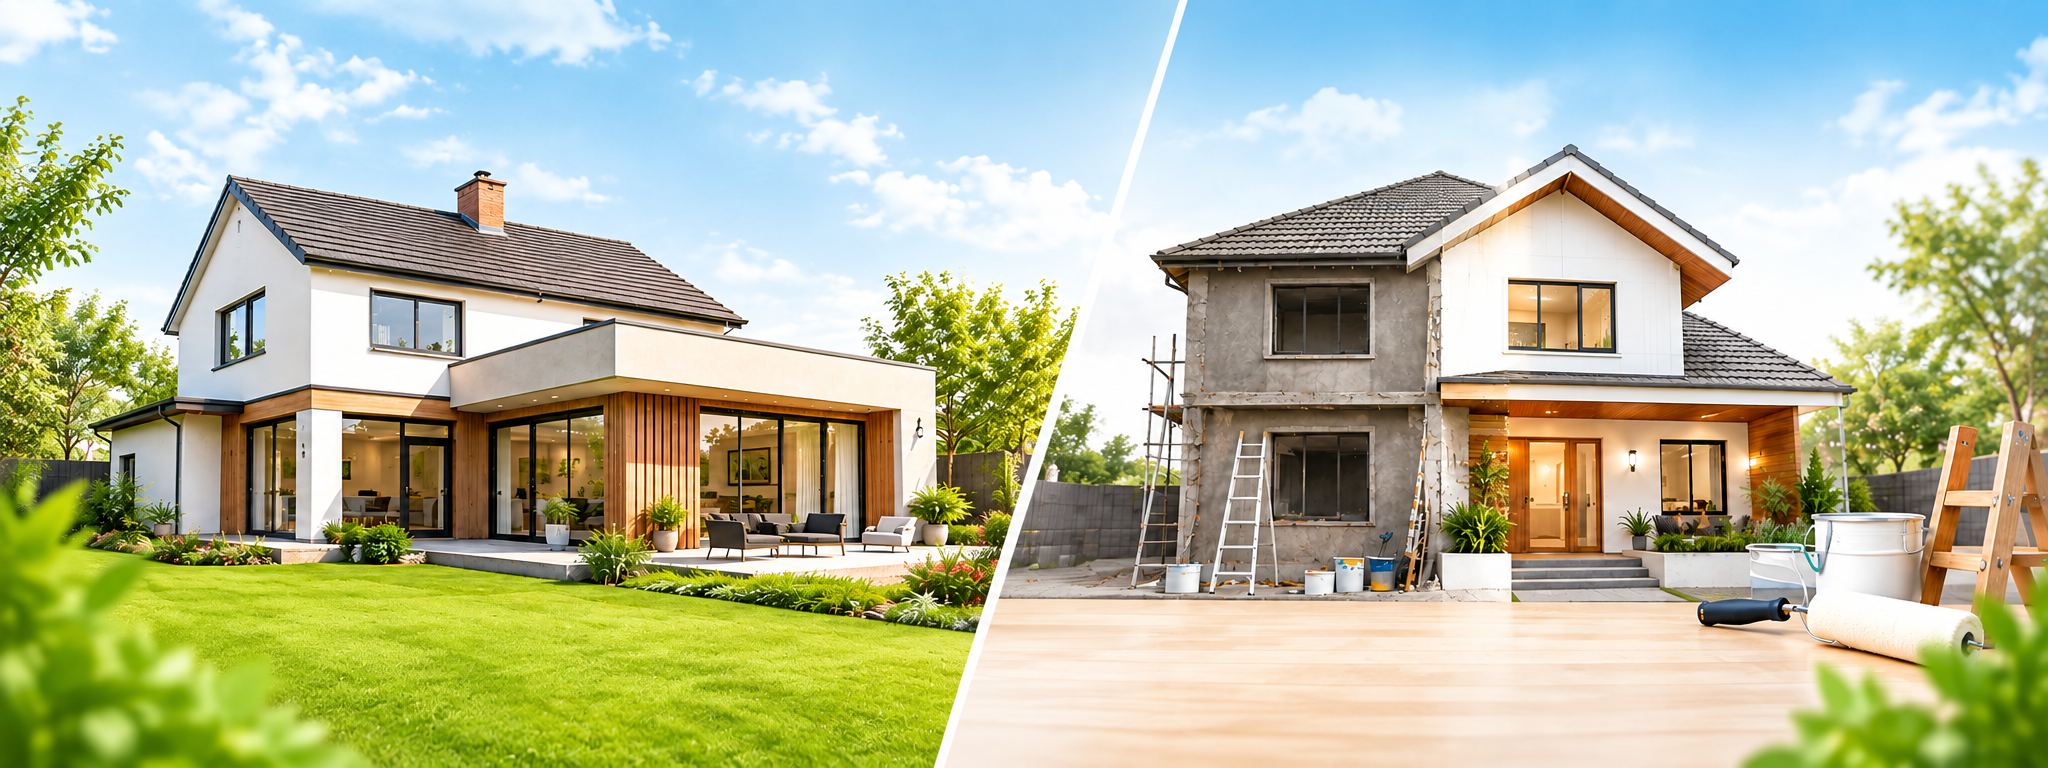
If your family has outgrown your current home, or your kitchen and bathrooms feel stuck in another decade, you are probably weighing a home extension loan against a home renovation loan — and wondering if they are even different products. They are, and the difference decides how much you can borrow, how the money is disbursed, and how quickly work can start. A home extension loan funds structural additions — an extra room, a new floor, a bigger balcony — while a home renovation loan (also called a home improvement loan) funds upgrades within your existing four walls, such as flooring, painting, or a modular kitchen. At Easy Home Finance, both are available as fully digital products with sanction in as little as 2 hours, so the real question isn’t which lender to trust — it’s which loan actually matches your project.
A home extension loan finances new construction — additional rooms, floors, or built-up area — and is disbursed in stages against construction milestones. A home renovation loan (home improvement loan) finances upgrades to your existing space — repairs, flooring, painting, kitchen or bathroom remodelling — usually disbursed as a lump sum against a contractor’s estimate. Both are secured against your property and available at Easy Home Finance starting at 8.99% p.a., with up to ₹75 lakh in funding and a 100% digital application.
What is a Home Extension Loan?
A home extension loan — often marketed alongside a home construction loan or self-construction loan — is for homeowners who already own a plot or existing house and want to add built-up area: an extra bedroom, a second floor, or an expanded kitchen. Because this involves genuine construction — foundations, walls, roofing, plumbing and electrical work — lenders treat it much like a plot and construction loan.
Funds are typically released in stages (commonly four to five tranches: foundation, slab, brickwork, roofing/plastering, and final completion) after a site inspection or engineer’s certification at each milestone. During this period, you pay pre-EMI — interest only on the amount disbursed — and full EMI begins only after the final tranche, keeping your outflow lower while construction is ongoing.
To apply for a construction loan or house construction loan in India, you’ll typically need an approved building plan, a municipal sanction, and a licensed architect’s cost estimate, alongside standard income and KYC documents. The best banks for construction loans and housing finance companies in India are the ones combining flexible, stage-wise disbursement with genuinely fast turnaround.
What Is a Home Renovation Loan (Home Improvement Loan)?
A home renovation loan — usually called a home improvement loan in India — funds work inside your existing walls: repainting, re-flooring, waterproofing, rewiring, or a kitchen and bathroom overhaul. There’s no increase in built-up area and usually no structural change, which is why approval for a home renovation loan across India is simpler than construction — lenders typically ask for a contractor’s estimate and ownership proof rather than architectural drawings.
Funds are usually disbursed as a lump sum, occasionally in two instalments for larger projects. When comparing home improvement finance companies, check two things: whether the loan is secured against your property (lowering the rate versus an unsecured personal loan), and how fast you can get a home improvement loan sanctioned. Easy Home Finance disburses home repair loans up to ₹75 lakh from 8.99% p.a., with minimal documentation and funds released within 24 hours.
Home Extension Loan vs Home Renovation Loan: Key Differences at a Glance
| Parameter | Home Extension Loan | Home Renovation Loan |
|---|---|---|
| Purpose | Adds new built-up area — extra room, floor, or extended space | Upgrades existing space — no increase in built-up area |
| Nature of work | Structural: foundation, walls, roofing, plumbing/electrical for new area | Non-structural: flooring, painting, fixtures, repairs, remodelling |
| Disbursement | Stage-wise, in 4–5 tranches against construction milestones | Usually a lump sum, occasionally 2 part-disbursements |
| Key documents | Approved building plan, municipal sanction, architect’s cost estimate | Contractor estimate, property tax receipt, ownership proof |
| Approval basis | Site inspection / engineer certification at each stage | Estimate plus income and KYC verification |
| Typical loan size | Higher, reflecting construction and material costs | Lower, reflecting refurbishment costs (can still run high for full remodels) |
| Tenure | Up to 20 years | Up to 20 years with a secured lender; shorter with unsecured options |
| Section 24(b) benefit | Up to ₹2 lakh/year on a self-occupied property, if completed within 5 years | Up to ₹30,000/year for repair or renovation loans |
Documents & Eligibility: What Lenders Actually Ask For
A home construction / extension loan typically needs a plot title deed, an approved building plan/municipal sanction, a licensed architect’s cost estimate, income proof, and digital KYC. A home improvement / renovation loan needs less — a title deed, latest property tax receipt, a contractor’s estimate, income proof, and digital KYC.
Eligibility for both is broadly similar: salaried individuals, self-employed professionals, and self-employed non-professionals can apply, with tenures from 5 to 20 years and the option to add a spouse or close family member as a co-applicant to boost eligibility.
Tax Benefits: What Section 24(b) Actually Allows
Under Section 24(b) of the Income Tax Act, interest on a loan used to construct, purchase, repair, or reconstruct a residential property qualifies for deduction. For a self-occupied property, this is capped at ₹2 lakh per financial year — but only if construction is completed within five years from the end of the financial year the loan was taken. Miss that window, and the cap drops to ₹30,000.
For a pure repair or renovation loan, the deduction stays capped at ₹30,000 per year regardless of timeline. Pre-construction interest can be claimed separately in five equal annual instalments once construction is complete, within the same ₹2 lakh ceiling. This deduction is generally unavailable under the new tax regime for self-occupied property, so confirm the current position with a chartered accountant before planning around it.
Which One Should You Choose — Extension or Renovation?
- Need more space? An extension loan adds real square footage and can boost rental income — useful if you’re a business owner needing a home office too.
- Need better space? A renovation loan modernises kitchens, bathrooms and flooring — often the fastest way to lift comfort and resale value.
- Already have a running home loan? Check if a home loan transfer with a top-up makes more sense — renovation or extension funds at the same rate as your transferred loan.
- Not sure which fits your budget? Use Easy Home Finance’s free eligibility calculator to see your maximum loan amount for either product in under a minute.
Why Homeowners Across India Choose Easy Home Finance for Both
Easy Home Finance is a housing finance company registered with the National Housing Bank and regulated under the RBI’s framework for HFCs. What sets the experience apart is how the loan is delivered:
- Fast, AI-powered approval — sanction decision in as little as 2 hours.
- Minimal documentation — no physical KYC or bank statements; everything is e-signed from your phone.
- 100% digital process — apply, upload, e-sign and track online, with disbursement in as little as 24 hours.
- Flexible eligibility — salaried, self-employed professionals, and self-employed non-professionals, tenures of 5–20 years.
- Funding up to ₹75 lakh, starting at 8.99% p.a., with doorstep assistance across 150+ branches.
Whether you’re planning a home construction / extension loan or a home improvement loan, you can check your exact eligibility using the free eligibility calculator before you apply.
Ready to build or upgrade? Apply Now to check your eligibility for a home extension or home renovation loan with Easy Home Finance.
Frequently Asked Questions
Q: What is the main difference between a home extension loan and a home renovation loan?
An extension loan funds new built-up area — an extra room or floor — disbursed in stages. A renovation loan (home improvement loan) funds upgrades within your existing space, disbursed as a lump sum.
Q: Can I claim a tax deduction on a home extension loan?
Yes, up to ₹2 lakh per year under Section 24(b) for a self-occupied property, provided construction is completed within five years of taking the loan.
Q: How much loan amount can I get for extension versus renovation?
Extension loans are usually sanctioned for higher amounts, since construction costs more than refurbishment. Easy Home Finance offers up to ₹75 lakh for either product, based on income and property value.
Q: Which loan is approved faster — extension or renovation?
Renovation is usually marginally faster, needing fewer approvals. At Easy Home Finance, both are sanctioned in as little as 2 hours via AI-powered underwriting.
Q: Do I need to own the property to apply for either loan?
Yes. You, or a co-applicant such as a spouse or close family member, must hold clear title to the property.
Q: Does Easy Home Finance offer both loan types?
Yes — a dedicated Home Construction/Extension Loan and a separate Home Improvement Loan, both up to ₹75 lakh, starting at 8.99% p.a., fully digital.
Q: Can I get a top-up if I already have a home loan elsewhere?
Yes. Transfer your existing loan to Easy Home Finance and add a top-up at the same rate — often faster than a fresh construction or renovation application.
Leave a Comment